Ghana has stabilised its economy, but the harder task of turning that stability into jobs and prosperity for ordinary people has only begun.
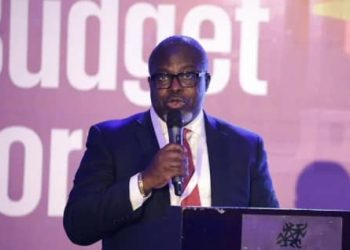
That was the message from the Ministry of Finance and the United Nations Development Programme (UNDP) at a post-budget forum organised by KPMG Ghana under the theme “The New Economy, New Ghana, Jobs and Prosperity.”
Delivering the keynote on behalf of the Finance Minister, the Ministry’s Coordinating Director for Technical Affairs, Samuel Danquah Arkhust, used a malaria analogy to explain where the economy stands.
Inflation, he said, is the fever, weak GDP is the loss of strength, and the IMF consultants and government are the doctors.
“The treatment has restored the stability, the new economy must build the resilience,” he told the gathering. “And the ultimate measure of our success must be the prosperity of every Ghanaian here present.”
He warned that the world is increasingly shock-prone, and noted that Ghana has had 17 IMF programmes since 1966. “Almost the entire life of the Fourth Republic seems to have been under an IMF programme,” he said.
KPMG Ghana’s Managing Partner, Andrew Akoto, cautioned that stability must be protected. “Ghana’s recognised economic stability must not be weakened by expenditure pressures, particularly as a political cycle advances in view,” he said.
UNDP Resident Representative Niloy Banerjee said a pre-budget survey kept returning to the cost of living and despondency about jobs. “The bottom line of this budget is clear. Stability done, macro doing okay. Now it’s down to democratising it… making it jobs and prosperity for all,” he said.
Mr Banerjee focused on micro, small and medium enterprises (MSMEs), which he described as the biggest generators of jobs. The problem, he said, is not ideas. “There is no lack of innovation, there is no lack of entrepreneurship. Finance is not forthcoming.”
He urged banks to offer patient capital, with repayment runways of a few years, now that liquidity has returned. “I think the time has come to be a little more adventurous with lending, with capital,” he said.
On agriculture, he pointed to cocoa and shea as high-employment crops. “One thousand metric tons of shea generate 20 to 40,000 jobs, mostly for women,” he said, adding that digital technology cannot match that.
Drawing on Malaysia’s oil palm industry, he said value addition must happen close to production and that land fragmentation must be addressed.
He also welcomed the proposed sovereign wealth fund, with a caveat. “Managed badly of course, it could become a slush fund for political patronage,” he said, but well-run funds “have been extremely powerful instruments of growth and economic stability.”